
Author: Andy Mohr Kia Team
Whether you are navigating a 23-minute commute into Indianapolis via U.S. Route 36 or planning family trips to Avon Town Hall Park, deciding how to pay for your new Kia is an important step. The choice between financing and leasing often depends on how much you drive around Avon, Brownsburg, Greenwood, and Carmel each year. At Andy Mohr Kia, we have established a long-standing presence in the community as a reliable, long-term automotive partner for drivers in Avon and nearby areas. We pair this trusted experience with specialized expertise in servicing and maintaining Kia vehicles, utilizing local knowledge to keep your car dependable. Understanding these payment paths ensures total confidence behind the wheel.
Key Takeaways (TL; DR)
Navigating the financial side of securing your next Kia doesn't have to be complicated. For drivers in the Avon area, understanding the differences between buying and leasing, leveraging specific incentives, and knowing your credit standing are the most effective ways to secure a monthly payment that fits your lifestyle. Here is a quick breakdown of what you need to know before signing.
- Credit Scores Drive Rates: Your credit history directly dictates the interest rates you qualify for. Improving your score before applying can significantly reduce your lifetime interest costs, leaving you with more spending money for weekend shopping trips at Avon Commons.
- Buying vs. Leasing: Financing a spacious model like the Kia Telluride builds equity over time until you own it outright. Conversely, leasing functions like a long-term agreement with typically lower monthly payments, making it a great option if you want to upgrade your cabin tech for that daily 23-minute commute down U.S. Route 36 every few years.
- Kia Finance Programs: Utilizing Kia's official lending channels opens the door to exclusive promotional APRs and flexible terms. Getting pre-approved online streamlines the process, so you spend less time doing paperwork and more time actually driving.
- Lease-End Flexibility: When a standard 36-month lease concludes, you have three distinct choices: buy the vehicle at its residual value, lease a newer model, or simply return the keys. This adaptability is perfect if your family is growing and you need to upsize from a compact SUV to a Carnival MPV for outings to Washington Township Park.
- Targeted Savings and Rebates: Specialized incentives can lower your out-of-pocket costs. Active military members, loyal Kia owners, and recent college graduates can often apply exclusive manufacturer rebates directly toward their down payment.
- Upfront Preparation: Arriving with the right documentation—such as two recent pay stubs, a valid driver's license, and active proof of auto insurance—eliminates delays. Establishing a firm budget beforehand ensures you negotiate loan terms that align comfortably with your household finances.
How Financing Your Kia Actually Works
Buying a vehicle through a traditional auto loan means borrowing the purchase amount from a lender like Kia Finance America or a local credit union, then paying it back over a set period known as your loan term. Typically ranging from 48 to 72 months, this timeline locks in a predictable monthly payment so you can comfortably budget your expenses. For Avon residents making the daily 23-minute commute down U.S. Route 36 or taking the kids to Washington Township Park in a spacious Kia Sorento, securing a loan provides an immediate path to long-term ownership. What this means for local drivers is you get the keys today while spreading the financial impact across several years of everyday driving.
As you make those monthly payments, you actively build equity—the portion of the Kia's total value that belongs entirely to you. Unlike a standard lease that might restrict you to a 10,000-mile annual cap, financing means you can take your Kia Sportage on endless weekend trips beyond Hendricks County without worrying about mileage penalties. Once you submit that final check, the lender transfers the vehicle title directly to your name, making the car yours free and clear. Whether you are loading up on weekly groceries at Avon Commons or adding all-weather accessories to tackle harsh Midwestern winters, buying your vehicle outright gives you total freedom over how you use and modify it.
How Kia Finance America Works for Your Next Vehicle

As the official lending partner, Kia Finance America is built to streamline how you fund your vehicle. For drivers around Avon, this means bypassing third-party banks to secure competitive loan rates and lease structures directly through the dealership. Because it operates as an in-house service, this pipeline frequently grants access to unique brand incentives, loyalty bonuses, and flexible payment plans tailored specifically for the Kia lineup.
Once you zero in on a vehicle—like a spacious Kia Telluride SUV for family outings at Washington Township Park or a sleek 2027 K5 sedan for smooth commuting down U.S. Route 36—securing the keys is simple. You can easily jump-start the paperwork by utilizing secure online pre-approval tools before you even step on the lot. Handling this step in advance means spending less time at a desk and more time enjoying your new ride.
Keep in mind that Kia Finance America evaluates factors like your current income and borrowing history to structure your final agreement. Because every buyer's financial background is different, exact offers and Annual Percentage Rates (APRs) will always vary based on your individual credit profile. Ultimately, leveraging these integrated services gives you the most direct, transparent path to getting behind the wheel.
Understanding the Mechanics of a Kia Lease
What exactly happens when you lease a new Kia? At its core, you are paying only for the portion of the car's lifespan that you actually drive, usually over a set window of 24 to 36 months. For Avon residents who log a standard 23-minute daily commute down U.S. Route 36, this arrangement means your monthly costs cover the vehicle's depreciation rather than its full purchase price. The leasing company determines your baseline payment by taking the original cost of the car and subtracting its projected worth at the end of your term—a figure officially called the residual value.
In addition to that core depreciation, your payments will include standard taxes and a rent charge known as the money factor, which operates much like the interest rate on a traditional auto loan. Because you are essentially funding just a few years of a model's life, comparing a lease to traditional financing for a vehicle like the Kia Telluride typically reveals a lower monthly financial obligation. This shorter commitment cycle makes it easier to upgrade to fresh hybrid powertrains and updated safety sensors every couple of years, providing an easy way to keep up with modern automotive technology while running errands around Avon Commons.
Navigating Your Kia Lease-End Options
As your contract nears its final months, you will need to decide on your next move. What this means for Avon drivers is having the flexibility to keep a vehicle they already know or seamlessly transition into something new. Whether your daily routine involves navigating U.S. Route 36 traffic or loading up the family for a weekend at Washington Township Park, you generally have three distinct paths forward once your term wraps up.
- Purchase Your Leased Kia: If you are perfectly happy with your current ride, you can buy it outright. The purchase cost is determined by the residual value stated in your original contract. That means if you’ve mostly driven short distances to Avon Commons and stayed well under your mileage limit, buying out your lease could be a highly practical financial decision.
- Lease or Finance a New Kia: Ready for an upgrade? You can turn in your current vehicle and start a fresh agreement on a new model. For instance, transitioning into a Kia Sportage Hybrid to maximize EPA-estimated fuel economy during a typical 23-minute commute into downtown Indianapolis is a popular choice for local professionals.
- Return Your Vehicle: You always have the option to simply hand the keys back. To avoid surprises, you'll need to schedule a complimentary lease-end inspection about 30 to 60 days before your turn-in date. This window gives you enough time to address any excess wear, tear, or mileage overages before officially closing the account.
What Is the Difference Between Financing and Leasing a Kia?

The core difference is simple: financing builds equity toward total ownership, while leasing covers just the vehicle’s depreciation over a specific timeframe—typically 24 to 36 months. For Avon drivers grabbing groceries at Avon Commons or commuting via Ronald Reagan Parkway, this decision dictates both your immediate monthly budget and your long-term mobility.
| Feature | Financing a Kia | Leasing a Kia |
|---|---|---|
| Ownership | The title transfers directly to you once the final loan payment is made. | The vehicle remains the property of the lessor and is returned later. |
| Monthly Payments | Generally higher, as your payments are calculated based on the full MSRP of the vehicle plus interest. | Usually lower, because you are only paying for the expected depreciation during the lease period. |
| Upfront Costs | A traditional down payment (often 10% to 20%) is standard to help reduce the total loan amount. | Typically requires only the first month’s payment, an acquisition fee, and a modest security deposit. |
| Customization | Full freedom to add aftermarket accessories, upgrade wheels, or modify the interior. | The vehicle must be returned in its original factory condition without permanent modifications. |
| Mileage | No restrictions—ideal if you frequently make long trips outside Hendricks County or into Downtown Indianapolis. | Fixed annual limits (typically 10,000 to 15,000 miles), with per-mile overage penalties if exceeded. |
| Wear & Tear | Dents and scratches will lower your eventual resale value, but they do not trigger direct fees. | Excess wear (like deep paint scratches or stained upholstery) results in specific lease-end charges. |
| End of Term | You own the car outright. Keep driving it payment-free, sell it, or trade it in. | Return the car, buy it out for its predetermined residual value, or start a new lease. |
The Core Variables Behind Your Kia Finance or Lease Terms
Ever wonder why two drivers might get slightly different rates on the exact same Kia Telluride? Your final contract conditions are shaped by a mix of your personal financial health and the specific vehicle you choose to drive home. Whether you are signing a standard 36-month lease or a traditional 72-month loan, lenders review a core set of variables to build your offer. For shoppers commuting down U.S. Route 36, understanding these moving parts means you can adjust your budget before heading to the dealership, keeping more money in your pocket for weekend plans around Avon.
- Credit History: Lenders look at your past borrowing behavior to gauge reliability. A strong credit profile generally unlocks the most competitive annual percentage rates (APR), significantly lowering the total cost of your vehicle.
- Initial Out-of-Pocket Payment: Putting more money down upfront—such as 10% or 20% of the purchase price—reduces the principal amount you need to borrow. This instantly shrinks your monthly obligation and cuts down on the interest that accrues over the life of the loan.
- Contract Duration: The length of your agreement acts as a sliding scale for your budget. Spreading a loan over 72 months instead of 48 makes your monthly payments much smaller, though you will ultimately pay more in total interest over those extra years.
- Model Selection and Promotions: The sticker price naturally dictates the size of your loan, but the type of vehicle matters, too. Opting for a new release, like an all-electric Kia EV9, frequently grants access to manufacturer-backed financing specials or lease incentives that aren't available for pre-owned models.
- Current Debt-to-Income (DTI) Ratio: Financial institutions compare your existing monthly debt obligations against your gross income. Keeping a manageable DTI reassures lenders that adding a car payment won’t stretch your finances too thin while you are out running errands near Avon Commons.
Can I Qualify for Special Kia Financing Programs?
Yes, Kia provides several specialized lease and financing incentives designed to make driving a modern, reliable vehicle more accessible. What this means for Avon drivers is that your personal background—whether you are just entering the local workforce or have served in the armed forces—could unlock meaningful savings on your next car. Many of these incentives can be combined with standard promotional rates, and you can review baseline national details on Kia's official website.
- Kia College Graduate Program: That fresh degree does more than look good on a wall. If you recently graduated from a university in Indianapolis or beyond, providing proof of your diploma and current employment can secure a helpful rebate. It’s a smart way to lower the financing costs on a stylish commuter, like a Kia K5 sedan, for your daily drives along U.S. Route 36.
- Kia Military Appreciation Offer: To honor the dedication of service members around Avon and Brownsburg, eligible active-duty military personnel, honorably discharged veterans, and their spouses can take advantage of exclusive rebates. This offer helps ease the financial transition into a spacious, road-trip-ready SUV like the Kia Telluride.
- Loyalty Benefits: Already have a Kia parked in the driveway? Current owners frequently receive loyalty savings when upgrading to a newer model. If your growing family is ready to swap an older vehicle for a Kia Carnival MPV before your next outing to Avon Town Hall Park, this program directly rewards your continued trust in the brand.
- Regional Promotions: Beyond national incentives, area-specific offers cycle periodically based on seasonal changes and inventory. These tailored financing terms and lease specials are structured specifically to benefit drivers navigating the changing weather and traffic patterns of Central Indiana.
Steps to Secure Your Kia Lease or Auto Loan

Wondering the fastest way to get behind the wheel of a new Kia? You can actually complete the bulk of your application from home before you ever turn onto U.S. Route 36. Whether you are aiming for a standard 36-month lease on a spacious Kia Telluride for weekend outings to Avon Town Hall Park, or a traditional 72-month loan on a fuel-efficient Niro Hybrid, the required steps remain exactly the same. By tackling the initial paperwork early, you spend less time waiting at a desk and more time enjoying your upgraded drive around Avon. Here is how the straightforward process works:
- Start with Pre-Qualification: Submit some basic information online to view your likely terms and interest rates. This step utilizes a soft credit check, meaning you can explore your budget options without impacting your current credit score.
- Compile Necessary Documents: Lenders require verification before handing over the keys. Gather a valid driver's license, current proof of auto insurance, and recent proof of income (such as a month of pay stubs). If you recently relocated within Hendricks County, be sure to bring a utility bill to verify your residence.
- Submit the Full Application: Once you settle on a specific vehicle and price, it is time to make it official. Submitting the formal application triggers a hard credit inquiry, which is required by financial institutions to generate your final, locked-in approval.
- Review and Sign Your Contract: Take a moment to read through your finalized paperwork. Verify your Annual Percentage Rate (APR), the total length of the term, your exact monthly payment, and any added vehicle service contracts before signing your name and hitting the road.
Cash vs. Financing: Funding Your Next Kia
Purchasing your vehicle outright has an undeniable appeal. When you hand over a check for a new 2027 Kia Seltos, you secure immediate ownership, avoid all interest charges, and instantly benefit from the peace of mind of Kia's standard 5-year/60,000-mile New Vehicle Limited Warranty. Bypassing a typical 60-month loan changes the equation completely by keeping thousands of dollars in your pocket over the long haul. That means your title is free and clear from day one, which is a great feeling when you're running weekend errands around Avon Commons. However, the obvious trade-off is liquidity; sinking a large lump sum into a vehicle ties up cash you might prefer to have on hand for unexpected home repairs or other financial priorities.
On the flip side, financing spreads your purchase into predictable monthly increments, keeping your personal savings liquid. Suppose you want the added efficiency of a 2027 Kia Sportage Hybrid for those daily commutes down U.S. Route 36. Taking out a loan lets you drive home in a highly capable SUV without completely depleting your bank account. You will pay interest over the life of the term, but preserving your cash buffer matters because it protects you against unexpected life events while you enjoy your new ride. For families in Hendricks County, choosing to finance often strikes the perfect balance between maintaining everyday financial flexibility and upgrading your trips to Avon Town Hall Park.
What Are the Pros and Cons of Each Payment Method?
Deciding how to pay for your next vehicle comes down to your daily driving habits and long-term financial goals. What this means for Avon drivers is weighing the flexibility and lower payments of a lease against the unrestricted mileage and equity-building power of a loan. Let’s break down the specific advantages and tradeoffs of each path.
Pros of Financing a Kia
- Complete Ownership Control: Once the loan is paid off, the vehicle is entirely yours to keep, trade, or sell whenever you prefer.
- Unlimited Mileage: Whether you commute daily down U.S. Route 36 or take long cross-country road trips, you never have to worry about mileage caps or overage fees.
- Freedom to Customize: Want to add a factory tow hitch to your 2027 Kia Telluride for hauling bikes and gear to Washington Township Park? Financing gives you the green light to modify the vehicle as you see fit.
- Building Long-Term Equity: Every monthly payment directly increases your ownership stake, setting you up with a valuable asset for future trade-ins.
Cons of Financing a Kia
- Higher Monthly Out-of-Pocket: Because you are financing the entire purchase price of the vehicle plus interest, your monthly payments generally run higher than lease installments for the exact same model.
- Post-Warranty Maintenance: Once Kia’s standard 5-year/60,000-mile New Vehicle Limited Warranty expires, you become fully responsible for the cost of major repairs and replacement parts.
- Absorbing Depreciation: All vehicles lose value over time. As an owner, you carry the financial risk of how much your car will actually be worth when it is finally time to sell.
Pros of Leasing a Kia
- Lower Monthly Commitment: Since you only pay for the vehicle’s expected depreciation during the lease term rather than its total sticker price, your monthly payments drop significantly.
- Always Driving the Latest Tech: Leasing allows you to upgrade every few years—perfect if you want the newest safety sensors, hybrid efficiency, or infotainment upgrades in a 2027 Kia Sportage Hybrid.
- Warranty Peace of Mind: Most lease terms last 24 to 36 months, keeping you comfortably inside the factory warranty window, meaning unexpected mechanical bills are virtually nonexistent.
- Hassle-Free Transitions: When your term ends, just hand the keys back to the dealership. There is no need to negotiate trade-in values or deal with private buyers.
Cons of Leasing a Kia
- Strict Mileage Caps: If your daily commute up Ronald Reagan Parkway pushes you past your agreed-upon limit (often 10,000 to 12,000 miles annually), you will face per-mile penalty charges at turn-in.
- Zero Equity Accrued: Similar to renting an apartment, your payments cover usage rather than building ownership, leaving you without a trade-in asset at the end of the contract.
- Wear and Use Fees: You must return the vehicle in excellent factory condition. Dents, scratched wheels, or interior stains beyond normal wear can result in end-of-lease bills.
- No Permanent Modifications: You cannot permanently alter the vehicle's appearance or performance, meaning those custom aftermarket accessories are strictly off-limits.
Smart Strategies for Securing the Right Vehicle Value

How you approach the buying process dictates what you actually pay over the life of your vehicle. For local drivers navigating the daily commute down U.S. Route 36 or planning family outings to Washington Township Park, locking in favorable financing terms means more money stays in your pocket. Knowing exact financial figures makes a massive impact—for example, the difference between a 5% and a 7.5% APR on a 60-month auto loan can shift your total out-of-pocket expense by thousands of dollars. Whether you want the spacious utility of a Kia Telluride or the hybrid efficiency of a Kia K5, here is how you can streamline the process and maximize your budget.
- Review Your Credit Report Early: Pulling your score a few months ahead of time lets you spot and dispute any reporting errors. A higher credit tier directly influences the interest rates you qualify for, keeping your monthly payments manageable.
- Compare Multiple Lenders: Do not just settle for the first approval you receive. Get a baseline quote from your local Hendricks County bank or credit union, then see if the dealership can beat it. Dealerships often have access to promotional Kia finance rates that standard banks cannot match.
- Strategize Your Purchase Timing: Automotive sales operate on monthly, quarterly, and annual cycles. Shopping late in the month or when fresh inventory arrives for the latest model year often brings enhanced incentives on existing stock.
- Anchor the Total Price First: Focus your initial discussion entirely on the total purchase price of the vehicle, independent of financing. Once you establish a fair baseline cost for that new Kia Seltos, you can safely transition to evaluating your trade-in and negotiating loan terms.
- Master the Financial Terminology: If you are taking out a loan, track the Annual Percentage Rate (APR), the exact length of the term, and the total amount financed. If you prefer to lease, familiarize yourself with the capitalized cost (negotiated vehicle price), residual value (projected worth at the end of the lease), and the money factor (the interest rate applied to leases).
- Assess Trade-In Value Independently: Before heading to the showroom, use authoritative resources like Kelley Blue Book or Edmunds to gauge current market values. Understanding what your outgoing car is worth gives you a distinct advantage when structuring your down payment.
Frequently Asked Questions (FAQs)
What should I expect during the financing process at Andy Mohr Kia?
The Andy Mohr Kia team guides you through our transparent "out-the-door" pricing approach to ensure a hassle-free car buying experience. Whether you are funding a spacious new SUV for family outings to Washington Township Park or a fuel-efficient sedan for your 23-minute commute into Indianapolis, our family-owned business organizes the transaction directly alongside you. We review every detail together, ensuring the professionalism our team is known for shines through at every step.
How does Andy Mohr Kia address customer feedback and ensure a positive experience with the finance team?
Because we believe our dealership is about caring for our neighbors, Andy Mohr Kia actively reviews customer feedback to maintain our high standard of professionalism. Our multilingual sales team works diligently to make sure every driver from diverse backgrounds feels completely at home during the entire process. If any questions arise, our staff addresses them immediately to ensure a smooth, transparent transaction aligned with our "out-the-door" pricing model.
How can I ensure I get the best financing rate?
Securing favorable terms stems from Andy Mohr Kia's commitment to transparent "out-the-door" pricing. Our multilingual sales team will review your profile alongside you to structure a financial plan that fits your household's budget. By letting our family-owned business organize the paperwork on your behalf, you can focus on enjoying your new Kia hybrid as you cruise down U.S. Route 36 or the Ronald Reagan Parkway.
What are the typical financing options available?
Andy Mohr Kia facilitates traditional purchasing and leasing agreements as a core part of our hassle-free car buying experience. Our professionals can outline terms that perfectly suit short daily drives or weekend shopping trips to Avon Commons, and you can even explore them remotely via our fully online buying experience. We will map out each step clearly using our transparent "out-the-door" pricing so you can confidently choose the pathway that best supports your lifestyle.
How does the Mohr to Your Door program work at Andy Mohr Kia?
Andy Mohr Kia offers a fully online buying experience through our Mohr to Your Door program, allowing you to secure your vehicle entirely from your living room. Our staff provides personalized video walkarounds of your chosen Kia and then coordinates convenient home delivery directly to your driveway. This hassle-free car buying experience makes upgrading your ride incredibly simple for busy professionals working from home around the Avon area.
How does Andy Mohr Kia support the local Avon community?
Serving the area since 2015, Andy Mohr Kia is deeply invested in giving back to our local community and supporting local charities. Our team proudly hosts community events, such as our annual Trunk or Treat, which provides a welcoming environment for families and pets alike. We believe that operating a family-owned business means going beyond automotive sales because it is truly about caring for our neighbors.
About Andy Mohr Kia
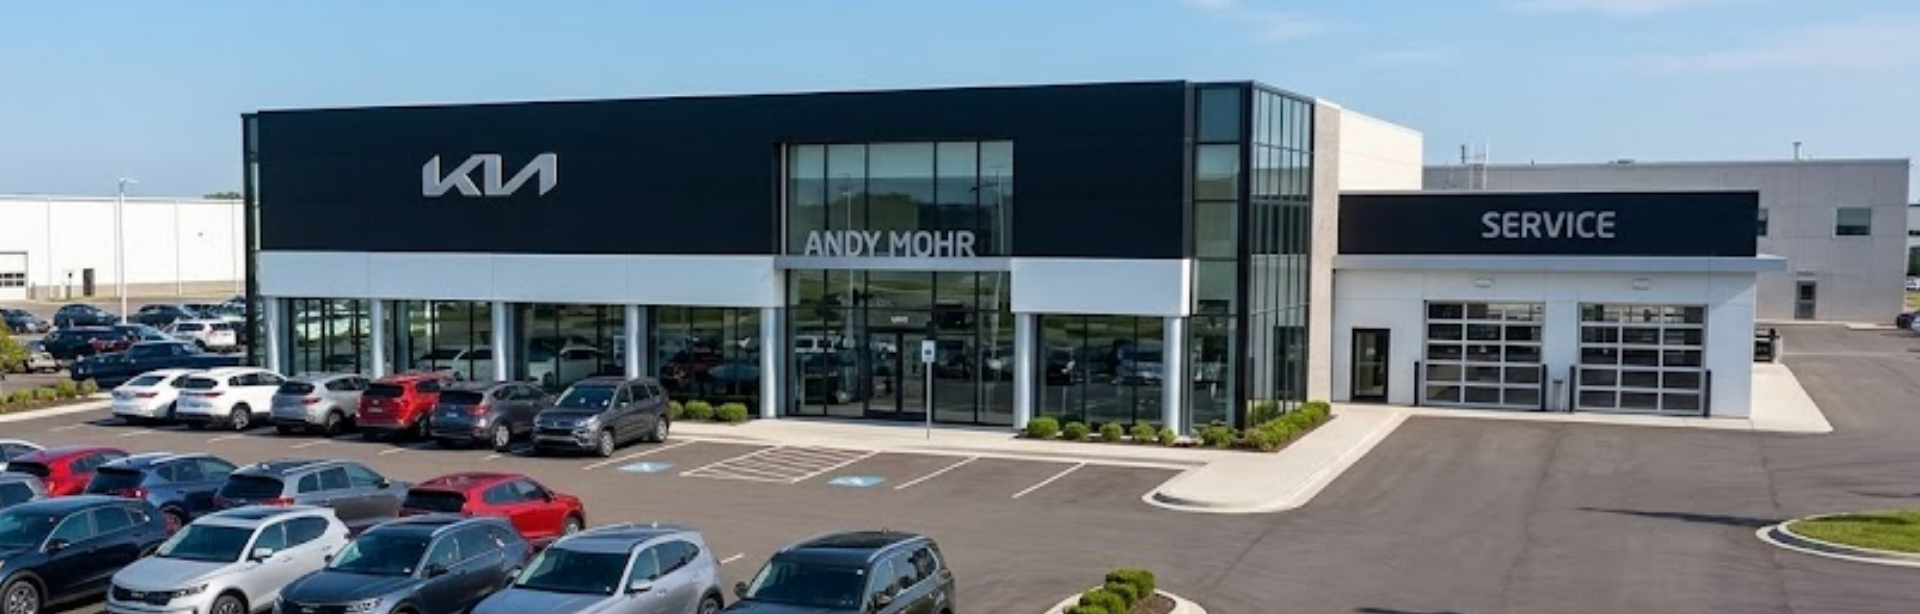
At Andy Mohr Kia, we pride ourselves on being more than just a car dealership; we're a dedicated part of the Avon community, committed to providing an exceptional, hassle-free car buying experience since 2015. As a family-owned business and a proud member of the Andy Mohr Automotive Group, we believe in transparent "out-the-door" pricing and offer a fully online buying experience through our Mohr to Your Door program, complete with home delivery and personalized video walkarounds. Our multilingual sales team, known for their professionalism, ensures our diverse community feels at home, while our award-winning service department offers express services, genuine Kia parts, and a welcoming environment for families and pets alike. We're deeply invested in our community, hosting events such as our annual Trunk or Treat and supporting local charities, because at Andy Mohr Kia, it's not just about cars, it's about caring for our neighbors.
Related Articles:
Your Comprehensive Guide to Locating a Kia Dealer in Avon, IN
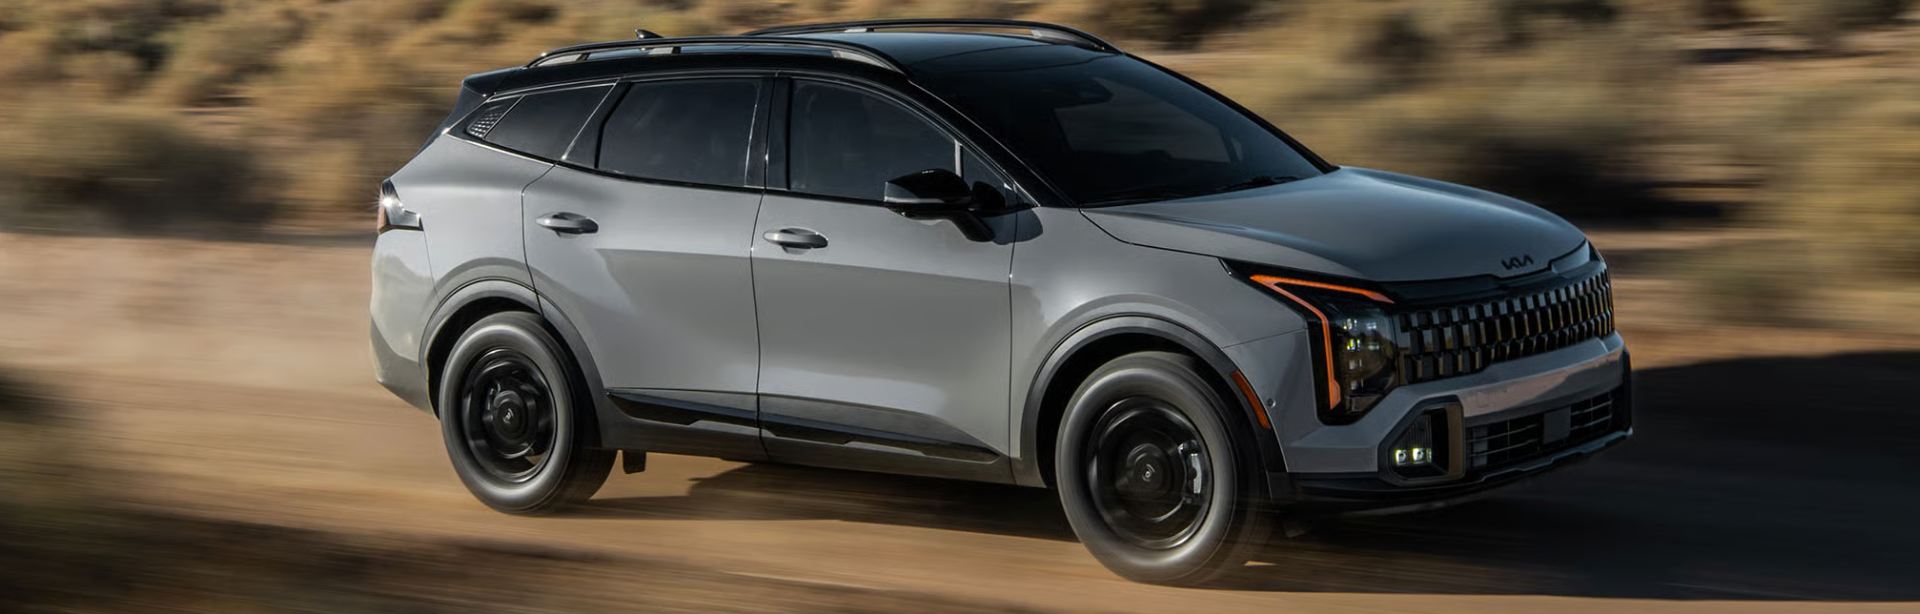
 Warranties include 10-year/100,000-mile powertrain and 5-year/60,000-mile basic. All warranties and roadside assistance are limited. See retailer for warranty details.